(14 August 2026 | Weekly) From Warning to Execution
The Institutional Confirmation of the Supply Deficit and the Materialization of Triple Chokepoint Pressure
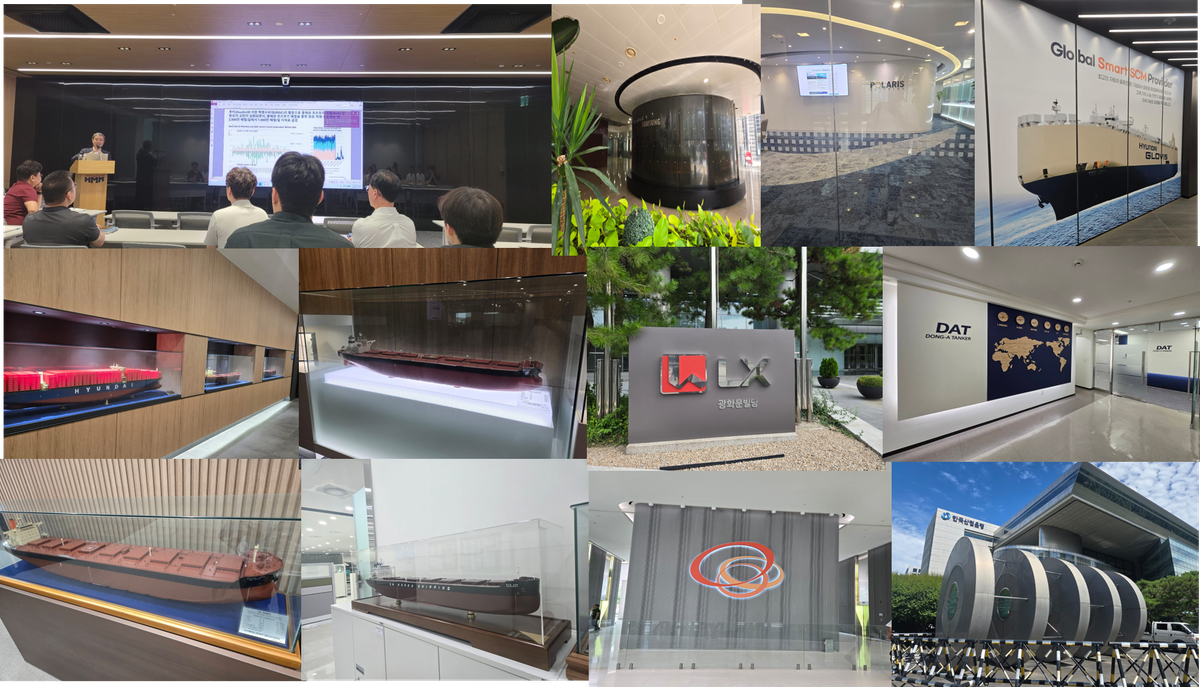
There is simply no substitute for meeting people in person. Every conversation brings a new perspective, and I have learned a great deal through the many discussions and exchanges of views over the past few weeks.
One question kept coming back to the centre of our conversations: When will the war in the Middle East end?
But perhaps the bigger question is what comes next. Even if the current crisis is eventually resolved, will similar disruptions continue to emerge elsewhere?
As geopolitical uncertainty becomes more persistent, inefficient logistics, longer and more complicated supply chains, and growing risk premiums can encourage precautionary buying and inventory building across commodity markets, potentially adding further upward pressure to prices.
At the same time, GCC countries are accelerating efforts to find alternative routes that reduce their dependence on the Strait of Hormuz. Put all of these pieces together— geopolitics, infrastructure, shipping, commodities, inventories and risk premiums — and the picture becomes increasingly complex.
At times, it felt as though the more we discussed, the deeper into the maze we went.
But that is also exactly why these conversations matter.
What made me particularly pleased was hearing from participants that, through our discussions, they had been able to develop their own views on where the market and supply chains may be heading. For an analyst, I can think of few more rewarding outcomes.
My sincere thanks once again to everyone across South Korea’s shipping, shipbuilding, finance, trading, steel and logistics industries who generously made time to meet and host me.
HMM · Hanwha Ocean · Samsung C&T · Pan Ocean · Hyundai Glovis · SM Group · LX Group · Dong-A Tanker · H-Line Shipping · Korea Ocean Business Corporation · Polaris Shipping · POSCO Group · POSCO International / POSCO Flow · Korea Development Bank
Thank you again for the hospitality, the challenging questions, and above all, the conversations.
(D+168) What I am watching
- BRENT NEAR $87 FRIDAY AFTER −2.2% THURSDAY / WTI ~$81 — DEAL ELUSIVE AS SHIP ATTACKS PERSIST — A two-day pullback from Wednesday's $89.61 peak: the market marking time between the deal that would break $80 and the rupture that would break $95, with the Aug 17 window now 3 days out.
- ZOLGHADR'S SIX CONDITIONS VS CITI'S FREEDOM-OF-NAVIGATION LINE — THE IMPASSE, CODIFIED — Iran's security council head: shut until the US meets six conditions, starting with ending the war against Iran and its allies. Citi's summary of the US line: no Iranian approvals, tolls, or controls. These aren't adjacent positions to be split — they're opposites, and every mediated text must pass through a needle both principals have formally welded shut. The impasse is no longer tactical hardening; it's doctrine.
- FRESH ATTACKS ON TANKERS AND ENERGY INFRASTRUCTURE — THE VETO PLAYERS STAY ACTIVE INTO THE WINDOW — The past week's incidents (ADNOC, Qeshm, Wafa, the sunken Indian vessel) have settled into a steady drumbeat. War-risk insurers price the drumbeat, not the drafts. The strait holds at 8-10 transits/day; Kharg stays dark.
- JEFFERIES MARKS THE CLIFF: A "FUDGE" DEAL IS PRICED — BUT "NOT SO BENIGN" IF THE DEADLOCK RUNS INTO NEXT WEEK — And next week is precisely where the window expires. The flagged accelerants: China's rising imports and Houthi attacks on Saudi infrastructure. Westpac, as month six begins: "Uncertainty remains high."
- THE WINDOW WEEKEND: WHAT AUG 17 ACTUALLY DECIDES — Whether the 60-day window dies as a dead letter inside a frozen war, gets extended as the first deliverable of a face-saving arrangement, or triggers the strike file (Pickaxe Mountain) that the siege pivot shelved but never cancelled — against a Supreme Leader unseen except on undated tape. Monday adds a milestone: the fourth attempt would pass Geneva's 14-day record, becoming the war's longest framework by surviving without resolving.
#StraitOfHormuz #SOH #News #Commodity #Shipping #Freight #Maritime #Oil #gas #fertilizer #grain #market #analysis #forecast
Weekly Commodities Review
From Warning to Execution — The Institutional Confirmation of the Supply Deficit and the Materialization of Triple Chokepoint Pressure
Crude Oil and Refined Products
The week's most consequential development was the institutional confirmation of the supply deficit. The IEA formalized a 4.3 million barrel per day (-4%) contraction in global crude supply this year, explicitly noting that last month's MOU collapsed within a month of signature and building its forecast on the premise that a Hormuz reopening remains distant. The figure sits far above the 1.5 million barrel shortfall indicated by the Reuters survey, and represents a multilateral body conceding that the supply crisis is now a long-duration condition rather than an episode. Combined with analysis identifying US refiners as the war's principal beneficiaries — on track for record margins again in the third quarter — the implication is that refining margin strength is structural, and will persist despite Trump's pressure on the industry.
The diplomatic track moved backwards, then hardened. Expectations built over the prior weekend around a near-complete Iran–Oman corridor agreement cooled within a day when Trump introduced an unprecedented demand for Iranian reparations, effectively countering Tehran's own conditions of compensation, sanctions relief and a halt to military threats. A negotiation in which both sides demand redress from the other is one that complicates exponentially. Iran subsequently responded that closure will be maintained until its conditions are accepted, and on the same day attacks were reported at two chokepoints simultaneously — the Gulf of Oman and the entrance to the Red Sea. The gap between Trump's repeated claims of an imminent deal and observable conditions continues to widen, and the market has adjusted accordingly: after five and a half months in which "imminent agreement" has failed repeatedly, prices now respond more to the frequency of physical attacks than to negotiation headlines.
What has muted the price reaction is the evidence of supply-side adaptation. OPEC July output recovered by 1.17 million barrels to 19.85 million, confirming a genuine buffer, while ADNOC Gas's 52% profit collapse illustrates both the real cost of the Hormuz closure and the fact that Gulf producers are restoring volumes through alternative routes. The market is repricing deadlock not as an immediate spike trigger but as stalemate under an already-adapted supply chain.
The conflict's institutional geography also shifted. Saudi Arabia concluded a mutual defence pact with Türkiye and Pakistan — an attack on one triggering a joint response from three — and the Houthis struck the Jazan refinery within two days. The sequence is instructive: the Houthi blockade produced not merely a Saudi bilateral response but a three-nation Sunni military alignment, and that alignment immediately provoked fresh attack. Geographic and institutional widening of the conflict means the energy risk premium is becoming a long-duration feature.
Natural Gas and LNG
US supply growth remains the only structural relief valve in a tight global market. Production is forecast to reach a record 111.2 billion cubic feet per day in 2026, and Venture Global's decision to raise annual guidance despite weak quarterly results signals industry conviction that the Middle East conflict's spot premium will continue to underwrite US exporter profitability.
More telling is a shift in the geography of gas trade itself. Middle Eastern buyers — from the world's largest gas-exporting region — are examining Canadian LNG on the Pacific coast as a geopolitical hedge. When exporters begin sourcing imports to insure against their own chokepoint, the Hormuz risk has stopped being a price variable and become a determinant of trade routing.
Grains and Oilseeds
The axis of the Black Sea war moved onto Russian export infrastructure. Ukraine struck the Novorossiysk naval base and two grain terminals, suspending operations at the primary gateway of the world's largest wheat exporter. With Russian August exports already at a ten-year low, the disruption illustrates a mutual attrition dynamic — Ukrainian export interdiction against Russian export interdiction — in which the entire grain market is held hostage. The Black Sea supply vacuum is now expanding in both directions.
On the Ukrainian side the damage was made official. The agriculture minister disclosed a downgrade of up to 12%, to 38–40 million tonnes, with APK-Inform following at -8.6%. This is the first time the effective halt of Odesa loadings since late July has been reflected in formal forecasts. The examination of rail transit via Moldova is the more revealing signal: it indicates that maritime export risk has crossed a threshold, accelerating a logistics reconfiguration in which large seaborne parcels disperse into overland and small-vessel routing.
Yet an important counterweight was introduced. Reuters analysis argued that the global food system is more resilient to a super El Niño than in past cycles, citing near-record inventories, technological improvement, and the emergence of Brazil and Russia — a direct counterpoint to the FAO index hitting a three-year high of 131.1, its strongest since January 2023. The grounding of the argument matters: both Russia and Ukraine are harvesting at scale even as exports collapse. Current grain strength is therefore a logistics blockage rather than a production shortfall, which carries a double edge — if the Black Sea unblocks, suppressed supply could arrive at once. Russian August wheat exports at a decade low plus negligible Ukrainian volumes equals a near-term vacuum, but grain is accumulating in both countries' warehouses.
The US supply picture reinforces this reading. The second-largest corn harvest on record is forecast, with acreage expansion offsetting a 2.3 bushel-per-acre yield decline — confirming the American capacity to fill the Black Sea gap. Sinograin clearing storage space through auctions in preparation for US purchases points the same direction, and visibility on fourth-quarter US-origin grain volumes is improving steadily. Against this, French corn was confirmed down 35% to its lowest since 1980, making European import demand the third leg of the trade.
Softs
Colombia's magnitude 7.4 earthquake constrained coffee exports, adding to an accumulating stack of soft commodity supply risk that now runs alongside the Black Sea disruption rather than independently of it.
Copper and Base Metals
Copper produced the week's symbolic milestone and its clearest transmission mechanism. Andy Home's column revealed that LME cash copper had already set an all-time high of $14,453.60 at the time of the Congo ban, with the three-month contract peaking at $14,527.50. His central insight — that the Congo panic says more about copper than about Congo — is the right frame: Congo exports concentrate, not refined metal, so the scale of the move is evidence of how fragile the broader market has become, with LME available inventory roughly halved in a month (202,000 to 101,000 tonnes, the lowest since January), continued outflows to the US, and collapsed treatment charges.
The physical transmission has now been confirmed. Antaike attributed a 2.83% decline in Chinese refined output in August — a second consecutive monthly fall — explicitly to severe raw material shortage, meaning the pathway from the Congo concentrate ban to Chinese smelter cuts is operating. With concentrate and refined inventory tightening simultaneously, upside risk continues to accumulate.
Critical Minerals and Resource Nationalism
The week clarified a producer-versus-consumer dynamic. In response to the Congo export ban, Trump announced $3bn in mineral investment, formalizing a "mineral superpower" competition, while Indonesia resolved confusion over rare earth inspections and resumed exports. The pattern — tightening control by resource holders driving accelerated domestic investment by consumers — is now the organizing logic of the sector.
Iron Ore and Bulk Mining
The Port Hedland strike, flagged as an open question for several sessions, executed. A 24-hour loading stoppage on Saturday was followed by a Sunday work stoppage joined by more workers, escalating into the first large-scale industrial action in 25 years. Two consecutive days of disruption at the world's largest iron ore export hub implies more than shipment delay; it signals prolongation risk in a wage negotiation already four months old. Even with Chinese July imports down 4% in a demand-soft environment, the supply disruption supports the downside in both iron ore prices and Capesize freight. The Capesize market's response early in the week — C5 premiums and the pace of loading resumption — is the immediate tell.
European Power and Inland Waterways
The continent's water crisis is developing into a multi-front constraint. Austrian water resources hit a century low, limiting hydro generation, and this connects to Hungary's Paks reactor cooling problem (which fell to 10% of capacity before turbine restart began) and to Danube barge logistics serving as Ukraine's alternative corridor. European power stress and grain logistics disruption are emerging from the same root cause, and Austrian rainfall-driven level recovery is therefore positive for grain movement as well as generation.
Freight and Shipping
The logistics blockage phase is generating route reconfiguration demand across segments. US, South American and Australian volumes filling the Black Sea vacuum, rising EU import requirements, and Chinese fourth-quarter US soybean liftings converge favourably for Panamax and Supramax grain cargo. Capesize is supported near-term by the Port Hedland disruption and by the accumulating tightness in the iron ore supply narrative. The caution is symmetrical: aggregate global volumes are declining, and a Black Sea normalization would invite a sharp reversal as suppressed supply clears.
Points to watch ahead:
- The oil price and OPEC+ response following the IEA's -4% forecast (production increases expected to halt from October)
- The pace of Novorossiysk terminal restoration and any further disruption to Russian wheat exports
- BHP Port Hedland follow-through — duration of the action, resumption of negotiations, and the Capesize freight response
- Whether LME three-month copper takes out the $14,527.50 record, and how far Chinese smelter cuts deepen
- Iran's response to the reparations demand and whether the Iran–Oman corridor agreement survives
- Resolution of the Ukraine–Moldova rail negotiation and the actual volume shifted overland
- Actual response from the Saudi–Türkiye–Pakistan alignment following the Jazan strike
- Whether a chain of export restrictions follows the FAO index at a three-year high
- Continued Chinese grain buying ahead of Xi's US visit (expected next month)
- Colombian port damage assessment and coffee prices
- Danube and Rhine water levels as a combined European logistics and power risk
- The timing of Chinese iron ore demand recovery after the steel maintenance season ends
Media coverage on the strait of Hormuz crisis
BRENT NEAR $87 FRIDAY AFTER −2.2% THURSDAY / WTI ~$81 — DEAL ELUSIVE AS SHIP ATTACKS PERSIST (Aug 13-14): Oil held its decline Friday as traders monitored efforts toward a Hormuz deal while fresh attacks on tankers and energy infrastructure kept the market on edge: Brent traded near $87 after falling 2.2% Thursday, with WTI around $81 — a two-day pullback from Wednesday's $89.61 peak. Iran and Oman have yet to reach an accord, after optimism earlier in the week that an agreement was within reach. The price action maps the stall precisely: the six-day fear rally has given way to a drift lower that reflects neither deal (which would break $80) nor rupture (which would break $95) — the market marking time against the Aug 17 window, now 3 days out, with the fourth attempt at day ~11 of a decay curve whose longest survivor (Geneva) died at 14.
2026.08.13–08.14 · Bloomberg / CNBC
ZOLGHADR'S SIX CONDITIONS VS CITI'S FREEDOM-OF-NAVIGATION LINE — THE IMPASSE, CODIFIED (Aug 10-14): The deadlock now has a formal architecture on both sides. Mohammad Bagher Zolghadr, head of Iran's Supreme National Security Council, says the strait remains shut until the US meets six conditions — including ending the war and aggression against Iran and its allies (with unfrozen funds, troop withdrawal, compensation, sanctions relief and route recognition rounding out the reported list). Citi's summary of the American line: any reopening must preserve unrestricted freedom of navigation "without Iranian approvals, tolls, or controls" — disputing the key elements of the reported arrangement. The two positions are not adjacent; they are opposites. Every mediated text (Oman's routes, Qatar's drafts, Pakistan's "arrangement") must thread a needle whose eye both principals have now formally welded shut. The impasse is no longer tactical hardening — it is doctrine on both sides.. Iran is also reportedly working with Oman on a framework for a permanent toll system for Hormuz. Trump rejected the toll proposal, insisting Hormuz must remain "open, free, and without toll charges." / Fox News
FRESH ATTACKS ON TANKERS AND ENERGY INFRASTRUCTURE — THE VETO PLAYERS STAY ACTIVE INTO THE WINDOW (Aug 13-14): The attacks that snapped the deal optimism did not pause for the deadline: fresh strikes on tankers and energy infrastructure kept the market on edge into Friday, and Citi flags that risks remain elevated outside Hormuz — with Houthi groups continuing attacks and threats against Saudi-linked shipping in the Red Sea and around Bab el-Mandeb. The pattern of the past week — the ADNOC vessel, Qeshm-area strikes, the Wafa, the sunken Indian vessel — has settled into a steady drumbeat rather than discrete incidents. For the arrangement Pakistan describes, this is the operational problem: any text that reopens a lane must survive actors who profit from its failure, and war-risk insurers price the drumbeat, not the drafts. The strait itself holds at 8-10 daily transits; Kharg remains dark.
2026.08.10–08.14 · CNBC / CNBC
JEFFERIES MARKS THE CLIFF: A "FUDGE" DEAL IS PRICED — BUT "NOT SO BENIGN" IF THE DEADLOCK RUNS INTO NEXT WEEK (Aug 11-14): Jefferies economist Modupe Adegbembo captured the market's exact position: traders remain "confident that we can get to some sort of agreement, even if it may be a fudge... It may not be a great agreement, but it may be something that allows more oil and more things to flow through the Strait of Hormuz." But that confidence is "time-sensitive" — and market moves won't be so "benign" if the current deadlock runs into next week. Next week is precisely where the Aug 17 window expires. The warning defines the cliff: prices remain well below the war's peaks (the July $100 break; spring highs above $110-120) because a fudge is still the base case — China's rising crude imports and Houthi attacks on Saudi infrastructure are the flagged accelerants if the strait stays closed past the deadline. Westpac's framing as the war enters its sixth month: "Uncertainty remains high."
2026.08.13–08.14 · Bloomberg / CNBC
THE WINDOW WEEKEND: 3 DAYS, TWO DOCTRINES, ONE FUDGE — WHAT AUG 17 ACTUALLY DECIDES (Aug 14): The war's most consequential weekend since the pause collapse begins with every element in place and nothing signed. The pieces: an Iran-Oman text (routes, coordinates) formally divorced from reopening; Zolghadr's six conditions against Citi's no-approvals-tolls-or-controls line; a formalized US siege (sanctions expansion + blockade enforcement) justified by the military campaign's failure to force capitulation; a Supreme Leader unseen except on undated tape; Pakistan insisting an arrangement is close; and a market priced for a fudge with a time fuse. What Aug 17 decides: whether the 60-day nuclear window — set when the June framework died — expires as a dead letter inside a frozen war, gets extended as the first deliverable of a face-saving arrangement, or becomes the trigger for the strike file (Pickaxe Mountain) that the siege pivot shelved but never cancelled. The fourth attempt would match Geneva's 14-day record on Monday — the day after the window closes.
2026.08.11–08.14 · CNBC / CNBC
MILITARY (August 14 / D+168): Deal elusive — Iran-Oman accord not reached after early-week optimism. Fresh attacks on tankers + energy infrastructure persist into the window. Zolghadr: six conditions before reopening. Citi: US line — no Iranian approvals, tolls, or controls. Siege formalized (sanctions + blockade). Houthi threats active (Red Sea / Bab el-Mandeb). Kharg dark; strait at 8-10 transits/day. Mojtaba: no dated appearance. Aug 17 window: 3 days. Fourth attempt: day ~11 (Geneva's 14-day record falls Monday). US KIA 17 / Wounded 427+. Blockade Day 125. Lebanon 4,219+. Total ~6,500+.
2026.08.14 · Bloomberg / CNBC
MARKETS (August 14 / D+168): Brent near $87 Fri (Thu −2.2%) / WTI ~$81 — two-day pullback from $89.61 peak; marking time between deal (<$80) and rupture (>$95). Still ~+21-24% vs pre-war. Jefferies: fudge priced, "time-sensitive" — not benign past next week. Flagged accelerants: China import demand + Houthi attacks on Saudi infrastructure. IEA 1.8M bpd shortfall stands; EIA +17.4M build anomaly; SPR below 300M. Gas $4.09. Gold above $4,100. Catalysts: Aug 17 window (3 days — the weekend event), Jackson Hole Aug 27-29, FOMC Sep 15-16. / Al Jazeera
WHAT COMES NEXT (August 14 / D+168): The window weekend. Key questions: (1) Does an arrangement — even a fudge — land before Sunday Aug 17, converting the window's expiry into an extension deliverable? (2) If nothing signs, what does expiry trigger Monday — Pickaxe Mountain against a weapons-willing Mojtaba, a formal window extension, or silence that confirms the freeze? (3) Does the fourth attempt outlive Geneva's 14-day record Monday — becoming the war's longest framework by surviving without resolving? (4) Do the veto players escalate into the deadline — the drumbeat of tanker and infrastructure attacks is the standing threat to any signature? (5) Does Jefferies' "not so benign" repricing begin Monday if the deadlock crosses the line — with $95+ the rupture zone? (6) Does Mojtaba appear — dated, live, signing — or does the window close on a leader the world has not verifiably seen since February?
2026.08.13–08.14 · Bloomberg / CNBC
THE WINDOW WEEKEND BEGINS: Brent near $87 Fri (Thu −2.2%) / WTI ~$81 — deal elusive; fresh tanker + infrastructure attacks persist. Zolghadr: SIX conditions before reopening. Citi: US line — no approvals, tolls, or controls. The impasse is now doctrine on both sides. Jefferies: fudge priced but "time-sensitive" — "not so benign" if deadlock runs into next week (= past the window). Westpac: sixth month, uncertainty high. Kharg dark; 8-10 transits/day. Pakistan: arrangement close. Aug 17 window: 3 DAYS. Fourth attempt day ~11 — Geneva's record falls Monday. Gas $4.09. US KIA 17 / Wounded 427+. Blockade Day 125. Lebanon 4,219+. Total ~6,500+.
2026.08.13–08.14 · Bloomberg / CNBC
Please note this content has been prepared with the assistance of AI and is based on publicly available information, intended for general informational purposes only. It may contain errors or inaccuracies. Users are advised to independently verify all information, data, and figures against original sources before relying on it.